Africa loses an estimated $5 billion annually to additional banking fees and settlement delays because intra-African payments are routed through correspondent banks outside the continent, exposing the cost of fragmented financial infrastructure to businesses and individuals attempting to trade across African markets.
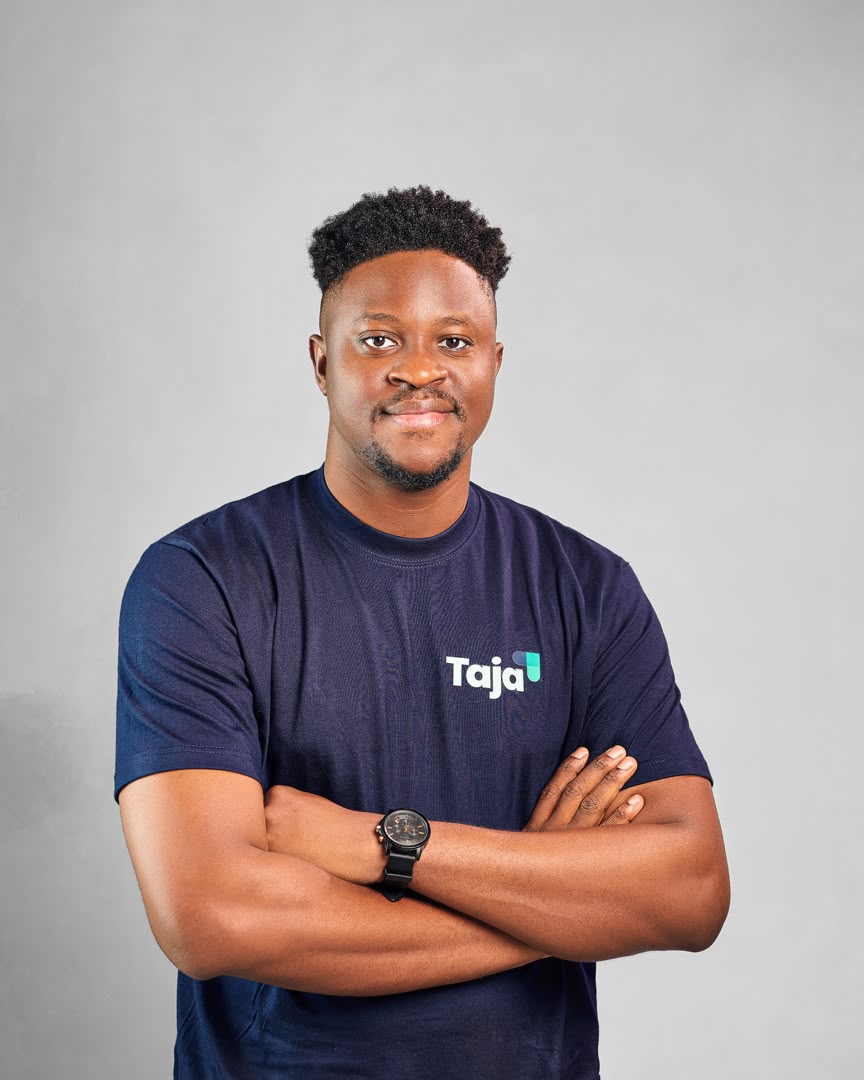
The problem is undermining efforts to deepen regional commerce, with intra-African trade accounting for just 15 percent of the continent’s total trade, compared with approximately 60 percent in Asia, according to figures cited by David Orovwiroro, chief executive officer and co-founder of Taja HQ, a financial technology company.
Read also: Where does a remittance live? The CBN’s data rule meets cross-border payments
Orovwiroro told BusinessDay that the reliance on Western correspondent banking networks means transactions between neighbouring African countries often pass through financial institutions outside the continent before reaching their destinations, adding costs, processing delays and foreign exchange complications.
The arrangement has created an expensive payment environment for businesses, freelancers and households that increasingly depend on cross-border transactions to participate in the continent’s growing digital and commercial economy.
The burden is particularly evident in remittances. An average $200 transfer to Africa costs 7.2 percent, according to the International Fund for Agricultural Development’s ‘Sending Money Home 2026’ report, significantly above the United Nations Sustainable Development Goal target of reducing remittance costs to below three percent.
With remittance inflows to Africa estimated at $124 billion, the difference between current transfer charges and the global development target represents a substantial amount of money that could otherwise support households, businesses and productive economic activities.
In some African corridors, the costs are considerably higher. World Bank figures cited by Orovwiroro indicate that sending $200 from Tanzania to neighbouring East African countries, including Kenya, Uganda and Rwanda, attracted average transfer fees of up to 33 percent.
These charges reduce the amount recipients receive and make smaller transactions particularly expensive for traders and individuals who rely on frequent payments across borders.
For African businesses, the consequences extend beyond remittance charges. Delayed settlements and multiple currency conversions complicate supplier payments, increase operating costs and weaken the competitiveness of companies seeking customers and partners in other African markets.
The problem also exposes a contradiction in Africa’s regional integration ambitions. While the African Continental Free Trade Area (AfCFTA) seeks to create a single market for goods and services, businesses still face fragmented payment systems and regulatory requirements when moving money between participating countries.
Orovwiroro argued that the continent needs a more integrated financial infrastructure that allows transactions to move directly between African currencies without relying excessively on the US dollar or correspondent banks outside the region.
He proposed a unified financial passport framework built around direct currency pairings, interoperable identity verification systems and locally connected payment infrastructure to make cross-border transactions faster and less expensive.
Under the proposed model, individuals and businesses would be able to hold multiple currencies, convert funds and settle payments in local markets without opening separate foreign bank accounts or navigating multiple layers of financial intermediaries.
The approach is already being explored by fintech companies seeking to address the continent’s payment fragmentation.
Taja, which launched in 2024, says it has grown to more than 50,000 active users across Nigeria, Ghana, Kenya, Senegal, South Africa, Benin and Côte d’Ivoire. The company processes millions of dollars monthly through its multi-currency wallets, cross-border payouts, currency conversion services and virtual accounts.
According to Orovwiroro, a Nigerian entrepreneur travelling to Ghana, for instance, can fund a wallet in naira, convert the funds into cedis and pay local merchants through mobile money or bank transfers without relying on cash or opening a Ghanaian bank account.
However, building a unified payment system across Africa faces significant structural challenges, particularly differences in financial regulations, currency liquidity and identity verification requirements.
Exchange rates between many African currencies are also derived through the US dollar, creating additional conversion costs and exposing transactions to liquidity constraints.
Read also: Africa’s fragmented data laws threaten cross-border digital trade as regulators push harmonisation
Orovwiroro said financial technology providers would need to work closely with regulators, banks and other financial institutions to establish compliant payment infrastructure capable of operating across multiple jurisdictions.
The success of such systems will depend on whether African countries can align regulatory requirements and develop payment networks that allow businesses to transact across borders with the same ease as domestic transactions.
For a continent seeking to expand regional trade, the challenge is no longer simply moving goods across borders but ensuring that the money used to pay for them can move just as easily.
Related News

Royal Ibeh is a senior journalist with years of experience reporting on Nigeria’s technology and health sectors. She currently covers the Technology and Health beats for BusinessDay newspaper, where she writes in-depth stories on digital innovation, telecom infrastructure, healthcare systems, and public health policies.
Source: